


Executive Summary
At first glance, the question “Who owns ChatGPT?” seems straightforward. It isn’t. Pose it to a room full of investors, engineers, journalists, and legal experts, and you will receive four differing—and fundamentally incomplete—answers. Each captures a fraction of the truth while missing the architecture as a whole.
This white paper argues that ownership of a modern AI enterprise like OpenAI cannot be reduced to a single individual, a solitary percentage, or a specific box on an organizational chart. Instead, it must be mapped across four distinct dimensions: the entity that operates the product, the legal entities that sit behind it, the parties holding economic equity, and the body exercising governance control. Conflating these dimensions fuels the most persistent myths in public discourse—from “Microsoft owns ChatGPT” to the assumption that the nonprofit’s minority equity stake somehow equates to majority control.
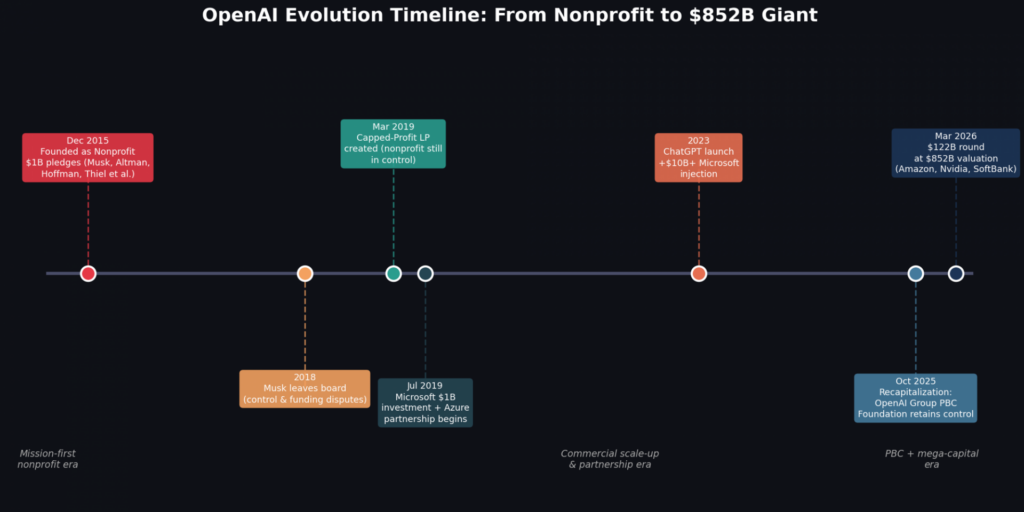
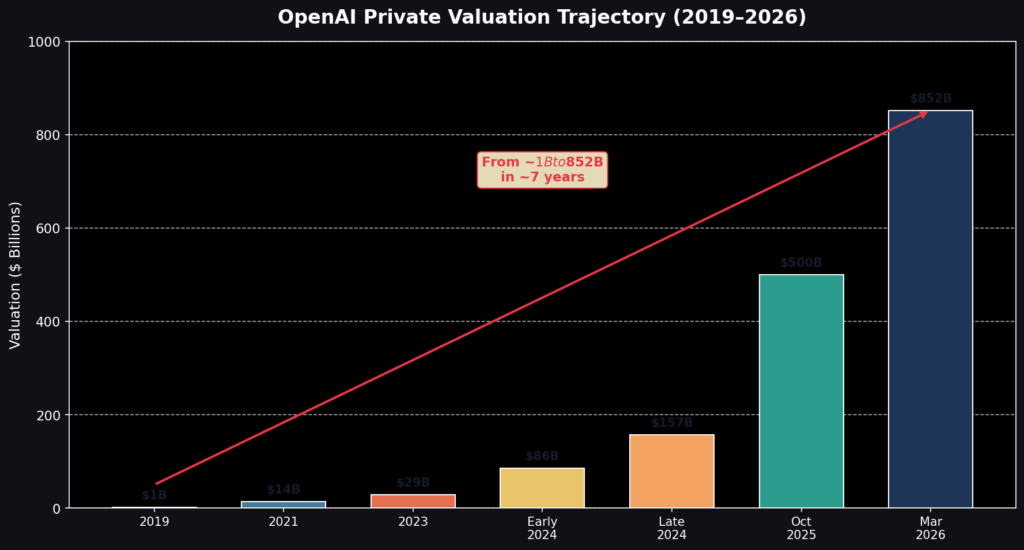
The stakes for structural clarity have never been higher. In October 2025, OpenAI formalized an arrangement where a nonprofit foundation controls a for-profit public-benefit corporation. By March 2026, a massive $122 billion committed-capital round at an $852 billion valuation diluted prior stakeholders and introduced new hyperscaler anchors, including Amazon, Nvidia, and SoftBank. Most recently, in June 2026, OpenAI’s confidential filing for a potential trillion-dollar IPO radically shifted the economic horizon, even as the core governance backbone remained deliberately unchanged.
Our central finding is grounded in the equity-governance separation principle: equity dictates economic participation, while governance rights dictate corporate control. These are legally distinct domains, intentionally firewalled within OpenAI’s structure. Furthermore, the true answer to “who owns ChatGPT” is rooted in structural design rather than volatile cap-table percentages. While equity figures go stale within months, the Foundation-to-operating-company control chain has withstood every major restructuring effort to date.
For executives, communicators, and market analysts, the mandate is clear: disaggregate the four dimensions of ownership, explicitly timestamp all equity claims, and separate durable structural reality from fleeting financial snapshots. This framework provides the blueprint to do exactly that.
- Introduction
- The Four Dimensions of Ownership
- The Equity-Governance Separation Framework
- Key Findings
- Recommendations
- Conclusion
Introduction
The Landscape
ChatGPT stands as one of the most consequential consumer products in modern technology, cementing OpenAI as one of the world’s most scrutinized private enterprises. Yet, the ownership dynamics of both remain chronically misunderstood—not due to hidden facts, but because the corporate structure defies traditional templates.
OpenAI breaks the standard mental model. It isn’t a conventional startup driven by founder equity, a standard public corporation reporting to shareholders, or a traditional non-profit. Instead, it operates as a sophisticated hybrid: a nonprofit foundation governing a for-profit public-benefit corporation, which subsequently interacts with users via regional operating entities. The result? Some of the world’s largest tech conglomerates hold massive economic stakes while wielding zero formal control.
This unprecedented structure is in a state of rapid evolution. Between October 2025 and June 2026, OpenAI navigated a corporate reorganization, secured over a hundred billion dollars in fresh capital, and laid the groundwork for an IPO aiming for a trillion-dollar valuation. Every single one of these milestones fundamentally altered the answer to “who owns ChatGPT”—but across entirely different dimensions.
The Problem
The confusion is largely conceptual. Mainstream analysis attempts to force four distinct legal questions into a single bucket:
- Who provides the end-user service?
- Which entity operates the commercial enterprise?
- Who holds the economic equity?
- Who dictates board composition and mission?
When you collapse these dimensions, predictable fallacies emerge. Microsoft’s heavy investment is mischaracterized as outright ownership. The Foundation’s governance authority is falsely attributed to majority equity. Confidential IPO preparations are mistaken for active public trading. A founder’s legacy and public prominence are confused with legal dominion.
These distinctions are far from pedantic. They are the legal reality that dictates who makes strategic technology decisions, who reaps the financial rewards, and what protections exist for future retail and institutional investors.
Why Now
As we navigate through 2026, clarifying this structure is an absolute necessity due to three primary catalysts:
First, the financial reality is outpacing public disclosure. The well-documented ownership breakdown from October 2025 was completely diluted by the historic March 2026 funding round. Because a refreshed cap table hasn’t been published, anyone citing the old percentages is relying on obsolete data.
Second, OpenAI is approaching the public markets. A confidential S-1 indicates that everyday retail and institutional investors may soon own a piece of the pie. This creates a historic friction point: what does “ownership” truly mean when public shareholders invest in a corporation legally bound to prioritize its original mission over their financial returns?
Third, misinformation is calcifying. Simplistic headlines—like “Microsoft’s AGI kill-switch”—propagate far faster than nuanced corrections. Operating on outdated assumptions leads to flawed business intelligence. Establishing a robust framework is the only way to avoid relying on yesterday’s headlines.
The Four Dimensions of Ownership
To accurately answer the ownership question, we must shatter it into its four component dimensions, each governed by specific entities.
Dimension 1: The Operator (Who Provides the Service)
From an end-user perspective, the service is contractually provided by OpenAI OpCo, LLC for users in the United States and most non-EEA regions. Different regional entities manage operations elsewhere. This geographical nuance is crucial: stating broadly that “users contract with OpenAI OpCo, LLC” ignores a massive segment of the global user base and immediately flags a lack of precision.
Dimension 2: The Legal Entities (What Sits Behind the Product)
The commercial engine driving the technology is OpenAI Group PBC, a public-benefit corporation. Legally, a PBC is mandated to weigh its foundational mission alongside pure profit—a distinction that will become the focal point of a future IPO.
Crucially, one must avoid the reductive claim that OpenAI Group PBC “owns all ChatGPT IP.” The exact distribution of intellectual property across OpenAI’s network of affiliates remains opaque. Operating the commercial entity is not synonymous with outright ownership of every underlying asset.
Dimension 3: Economic Stakeholders (Who Holds Equity)
When the public asks “Who owns ChatGPT?”, they are usually asking about this dimension. It is also the dimension most fraught with inaccuracies because equity is fluid.
Key Insight:
The last official, public cap table snapshot is from October 28, 2025. Any percentages cited without that specific timestamp are likely conflating historical data with current reality.
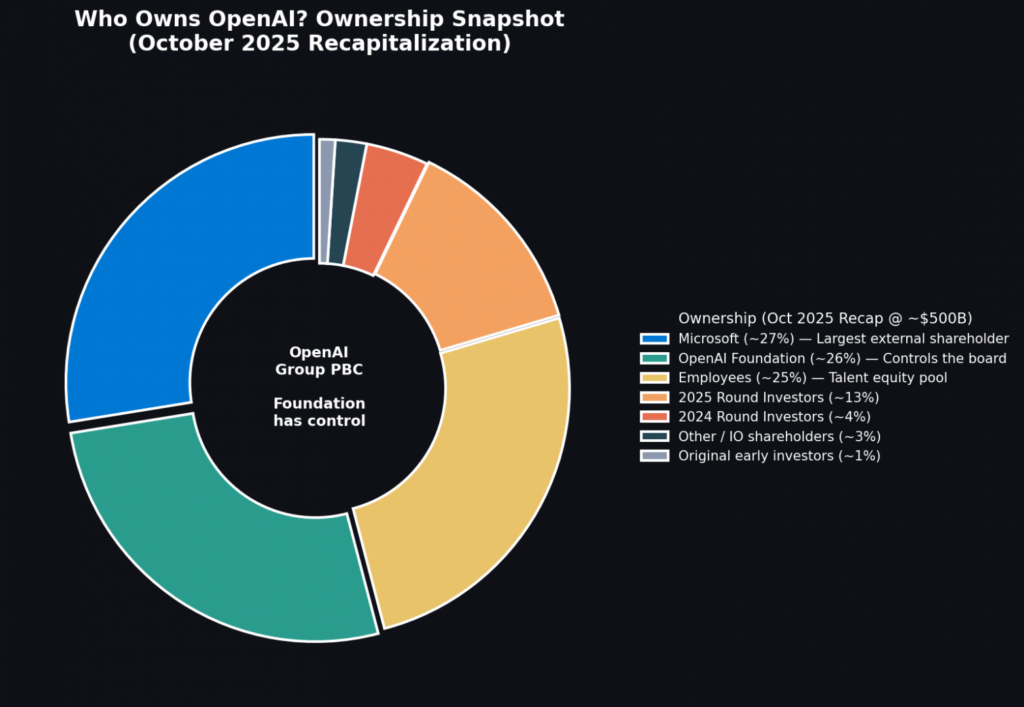
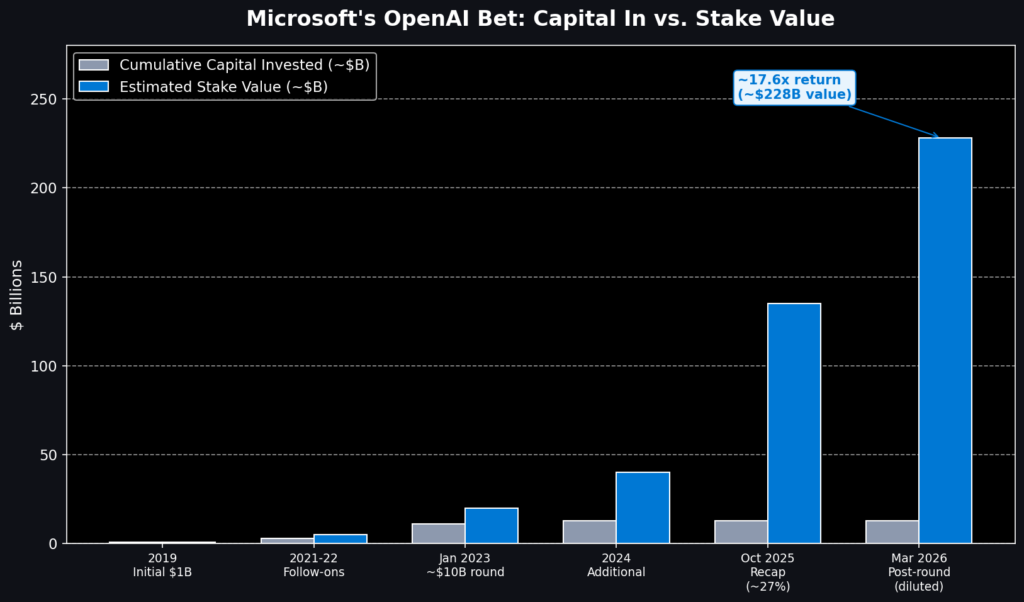
During the October 2025 recapitalization (valuing the company near $500 billion), OpenAI revealed an ownership breakdown across three primary cohorts:
OpenAI Economic Ownership Snapshot (Oct 28, 2025 – Pre-Dilution)
| Ownership (%) | |
| Microsoft | 27 |
| OpenAI Foundation | 26 |
| Employees and other investors | 47 |
Estimated economic ownership of OpenAI as of October 28, 2025.
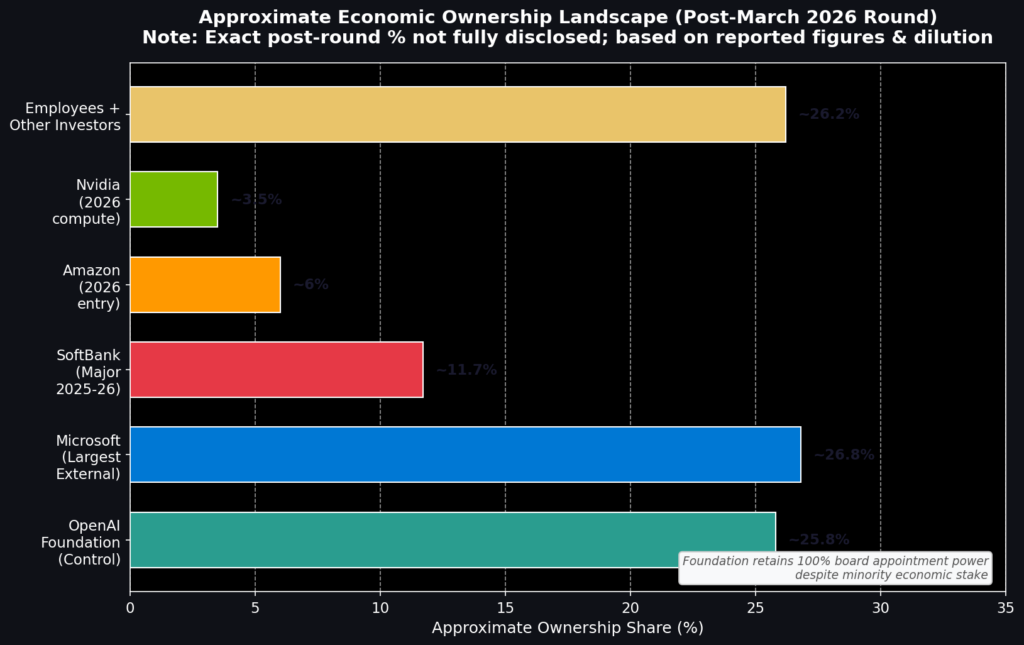
These percentages represent a snapshot in time, not today’s truth. On March 31, 2026, OpenAI closed a monumental $122 billion committed-capital round at an $852 billion post-money valuation. This round introduced massive new anchors: Amazon (committing up to $50 billion, heavily tied to IPO/AGI milestones), Nvidia, and SoftBank (roughly $30 billion each). This sheer influx of capital heavily diluted the October 2025 baseline, shattering the old Microsoft vs. Foundation dichotomy into a fragmented, multi-player cap table.
As of mid-2026, the exact, post-dilution cap table remains a closely guarded secret. The precise current percentages are simply unknown to the public.
Dimension 4: Governance Control (Who Controls the Board and Mission)
Absolute control belongs to the OpenAI Foundation. The nonprofit’s authority is baked into the structural DNA of the organization, entirely divorced from its economic equity. The Foundation appoints (and can remove) the board of OpenAI Group PBC, regardless of how much capital external investors pour in. The power stems from governance rights, not a 26% equity stake.
This governance architecture has proven incredibly resilient. Despite intense structural pressure and external scrutiny (including inquiries from state attorneys general) throughout 2024 and 2025, OpenAI officially reaffirmed in May 2025 that the nonprofit would retain ultimate control over the commercial arm. The structural backbone remains unbroken.
The Equity-Governance Separation Framework
The definitive takeaway from this analysis is this foundational rule:
Key Insight:
Equity dictates economic participation; governance rights dictate corporate control. They are legally separated concepts, and OpenAI’s architecture relies on keeping them permanently divided.
Grasping this principle immediately resolves the rampant misinformation surrounding ChatGPT’s ownership.
Applying the Framework to Common Claims
Using the Equity-Governance framework, we can easily debunk the four most prevalent ownership myths:
| Claim | The Flawed Logic | The Reality (Framework Corrected) |
|---|---|---|
| “Microsoft owns ChatGPT” | Because they invested billions and held the largest external stake, they run the show. | Microsoft holds significant equity, a non-exclusive license, and deep cloud integration—but zero governance authority over the board or core mission. |
| “Sam Altman owns OpenAI” | He is the prominent CEO and face of the company. | CEO is an executive function, not legal ownership. Public filings do not indicate a controlling, quantifiable personal equity stake. |
| “The Foundation controls it because of its 26% stake” | Control requires majority economic ownership. | Control is derived purely from structural board-appointment rights, entirely independent of their equity percentage. |
| “An AGI declaration severs Microsoft’s access” | Early licensing clauses contained an AGI threshold “kill-switch.” | The clause was successfully amended. AGI is now a verification milestone, not a termination event (details below). |
The Corrected AGI Module: Verification Event, Not Kill-Switch
One specific narrative requires urgent correction, as it is widely cited but completely obsolete.
The original 2019 agreement theoretically allowed OpenAI to sever Microsoft’s access to its IP upon a unilateral declaration of AGI. This “kill-switch” made for great headlines but is no longer legally relevant.
Through key amendments (October 2025 and April 2026), this clause was fundamentally neutralized. The unilateral declaration was replaced by an independent-panel verification requirement. Furthermore, Microsoft’s access was contractually guaranteed through 2032, with IP rights explicitly covering post-AGI models (subject to aligned safety guardrails).
The accurate narrative is:
An AGI declaration functions as a verification and contractual milestone—not an immediate termination of Microsoft’s licensing rights. While it may alter revenue-sharing timelines, it does not act as a kill-switch.
It’s important not to confuse this with Amazon’s massive $35 billion contingent tranche, which is specifically bound to an IPO or AGI milestone. Amazon’s terms are vesting conditions, completely separate from Microsoft’s licensing framework.
The Practical-Reality Caveat
Our framework maps de jure (legal) control. However, practical analysis requires acknowledging operational realities.
Legal governance does not negate sheer operational dependency. ChatGPT consumes an astronomical amount of compute and capital, tightly intertwining OpenAI with partners like Microsoft and Amazon. While investors lack formal board votes, decisions that aggressively threaten investor capital could trigger practical consequences—such as withheld resources or immense partner friction. This soft power is real.
However, soft power shouldn’t be mistaken for legal authority. The equity-governance separation remains the legal truth. The sensational “kill-switch” stories proved false, while the structural reality of the Foundation’s control remains the defining characteristic of the company.
Key Findings
- Ownership is Multi-Dimensional: It comprises the operator, legal entity, economic stakeholder, and governance controller. Collapsing these dimensions creates immediate inaccuracies.
- Equity Does Not Equal Control: The OpenAI Foundation retains absolute enterprise control through board-appointment rights, proving that structural authority is purposefully divorced from economic stake.
- Equity Figures Are Highly Volatile: The widely cited October 2025 breakdown (Microsoft ~27%, Foundation ~26%) was heavily diluted by the $122 billion March 2026 funding round. Current cap table percentages are unknown.
- The AGI Kill-Switch is a Myth: Amendments in late 2025 and 2026 transformed the AGI trigger into a verification milestone, safeguarding Microsoft’s technological access through at least 2032.
- An IPO Presents Novel Structural Tensions: Bringing a mission-bound Public Benefit Corporation to the public markets creates unprecedented dynamics, asking retail investors to back a board legally constrained from prioritizing profit maximization.
- Structure Survives While Percentages Shift: The control chain (Foundation → PBC → Operating Entity) has survived multiple crisis points and massive funding rounds, proving that structural governance is the only stable metric of ownership.
Recommendations
For Communications and Content Teams
- Always timestamp equity claims. Never use October 2025 data as a current benchmark. Use precise labeling: “As of October 28, 2025 (pre-March 2026 dilution).”
- Maintain regional accuracy. State clearly that operations fall under “OpenAI OpCo, LLC in the U.S. and most non-EEA regions” upon first mention, to ensure legal precision without sacrificing readability later.
- Prioritize structure over numbers. Cap tables are volatile; the Foundation-to-PBC framework is the durable truth. Lead with the architecture.
- Utilize “Last Verified” disclaimers. Protect your content’s integrity against sudden leaks or updated SEC filings by explicitly dating your analysis.
For Analysts and Investors
- Decouple licensing and investment terms. Microsoft’s 2032 licensing extension and Amazon’s IPO/AGI contingent investments are entirely separate instruments. Treat them as such.
- Differentiate “committed capital” from liquid cash. A $122 billion round often includes aggressive tranches, performance conditions, or heavy compute credits rather than pure cash deposits.
- Analyze the structural paradox critically. The tension of a mission-first PBC entering public markets is profound, but it should be analyzed as a structural reality, not speculative panic over sealed documents.
For Operators Tracking the Story
- Look for the unsealing, not the draft. Confidential S-1s do not trigger public database alerts. The actionable event is the transition to a public S-1 ahead of the roadshow.
- Automate for public transition events. Focus monitoring tools specifically on SEC unsealing alerts and official company newsrooms rather than futile searches for confidential drafts.
Conclusion
We began with a deceptive question: Who owns ChatGPT? The reality is that “ownership” is too blunt an instrument to capture OpenAI’s complex legal and financial realities.
ChatGPT is fundamentally an OpenAI product. In the U.S. and non-EEA regions, users engage with OpenAI OpCo, LLC. The broader commercial machinery runs through OpenAI Group PBC. The economic upside is fractured among legacy tech giants like Microsoft, the foundational non-profit, early employees, and new titans like Amazon, Nvidia, and SoftBank—in fluid percentages that remain masked from public view following the March 2026 capital influx. Yet, above it all, absolute governance remains firmly in the hands of the nonprofit OpenAI Foundation, fully insulated from the billions injected into the cap table.
The Equity-Governance separation is the lens through which this entire ecosystem makes sense. It clarifies why Microsoft’s billions don’t buy control, why a minority non-profit stake wields absolute power, and why an upcoming IPO will shift wealth generation without altering the fundamental command structure.
The percentages will inevitably fluctuate. The unsealing of the S-1 will eventually provide the first hard financial truths since October 2025. But the architecture is built to last. However the financial pie is ultimately sliced, public shareholders will gain economic exposure, but they will not gain the steering wheel.
This paradigm extends far beyond ChatGPT. As advanced AI continues to scale, understanding the firewalls between economic ownership and governance control will be mandatory for navigating the future of tech infrastructure. Moving forward, the question isn’t simply “who owns it,” but rather, “who owns which dimension of it?”
Last verified: August 4, 2026. This analysis reflects publicly available information and structural realities as of the publication date. The single event most likely to materially update the economic dimensions is the public unsealing of OpenAI’s S-1 registration statement.
